On 19 November 2026, Union Labour Minister Dr Mansukh Mandaviya chaired the 240th meeting of the Central Board of Trustees (CBT) of the Employees' Provident Fund. It approved a Systematic Withdrawal Plan (SWP) that lets a retiring member draw provident fund savings in instalments instead of one lump sum. It also cut the minimum balance rule from 25% to 10% and the waiting period for final withdrawal from 12 months to 2 months. The exam asks about the structure behind such headlines: what the three EPFO schemes are, who pays into them, which law backs them and where they sit among India's other social security schemes.
One Wage, Three Pots: EPF, EPS and EDLI
By Hitendra Deswal · Economics faculty, The Cavalier
The Employees' Provident Funds and Miscellaneous Provisions Act, 1952 created the Employees' Provident Fund Organisation (EPFO), a statutory body under the Ministry of Labour and Employment. The Act applies to establishments with 20 or more employees. A worker whose wage is within the wage ceiling must be enrolled.
| Pot | What it gives | Who pays in | Legal base |
|---|---|---|---|
| EPF (provident fund) | A savings corpus with interest, paid on retirement, resignation or other grounds allowed by the rules | Employee 12% of wages; the rest of the employer's 12% after the pension share | EPF Scheme, 1952; re-notified as the EPF Scheme, 2026 |
| EPS (pension) | A monthly pension after service, plus family pension | Employer only: 8.33% of pensionable wage, plus a government top-up | Employees' Pension Scheme, 1995 |
| EDLI (insurance) | A lump-sum payment to the family if the member dies in service | Employer only (a small percentage, about 0.5%); the member pays nothing | EDLI Scheme, 1976; now the EDLI Scheme, 2026 |
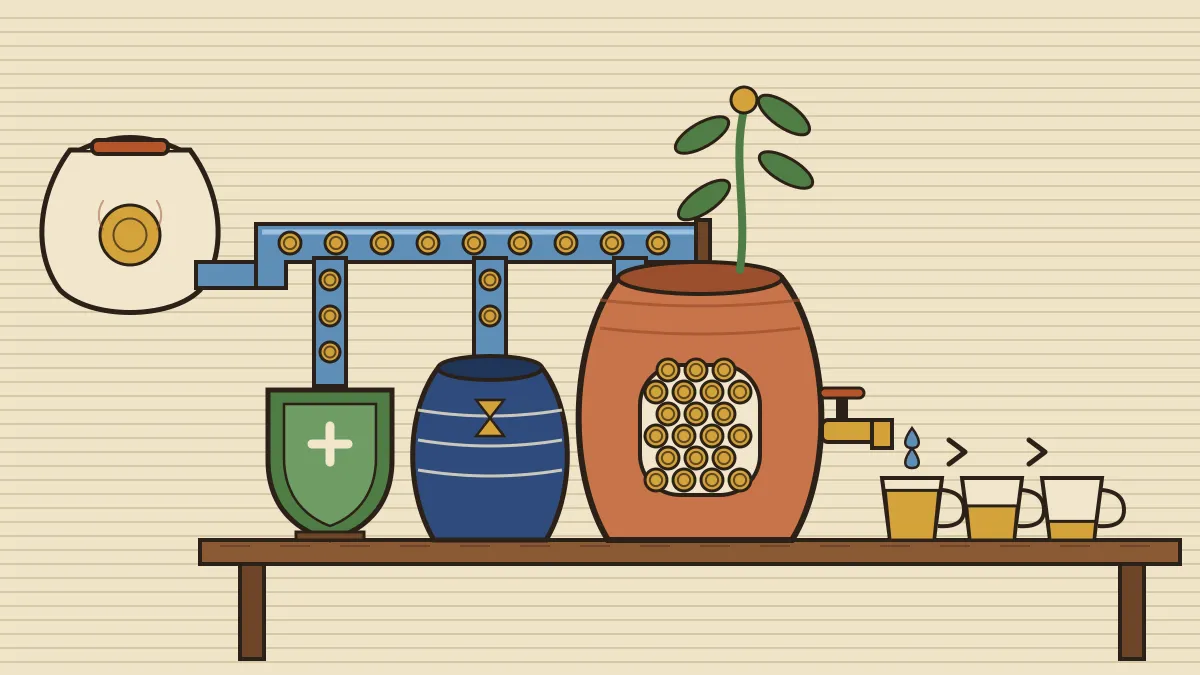
The structure to remember is simple. The employee pays 12%, all of it into EPF. The employer also pays 12%, but this is split: 8.33% goes to the pension (EPS) and 3.67% to EPF. The employer's 12% is not an extra charge on top.
EPS is calculated on a capped pensionable wage. In the long-running pension rule, the monthly pension equals pensionable salary × pensionable service ÷ 70, and a member generally needs 10 years of service to qualify, with the pension starting at 58.
Only EPF carries the employee's own contribution. EPS and EDLI are paid entirely by the employer (EPS with a government top-up). A question that says "the employee contributes to EDLI" is wrong, however natural it sounds.
On 16 September 2026 the Union Cabinet raised the wage ceiling for mandatory EPFO coverage from ₹15,000 to ₹25,000 a month. The ceiling had last been revised in September 2014. The change brings more than 51 lakh additional employees within mandatory provident fund, pension and insurance cover. See our article on the ceiling.
Who Runs the Money: the CBT, the UAN and the Investment Rules
EPFO is governed by the Central Board of Trustees (CBT), a tripartite body: representatives of the Central and State governments, of employers and of employees. It is chaired by the Union Minister of Labour and Employment, and the Central Provident Fund Commissioner (CPFC) serves as its Member Secretary. The Board decides the investment pattern and recommends each year's interest rate, which takes effect after the Finance Ministry approves it.
Every member holds a Universal Account Number (UAN). It is a single number for life, so a worker who changes jobs carries the same account and the corpus moves with the person. Provident fund money is invested mainly in government securities and other debt, with a limited share in equity-linked instruments. On 19 November the Board approved, in principle, investment of up to 3% of fresh accretion in eligible Alternative Investment Funds (AIFs), within the overall ceiling and initially through government-backed entities.
Some large employers run their own provident fund trusts, called exempted establishments. On 19 November the CBT reviewed 27 surrenders and four cancellations of exemption. About ₹5,996 crore of savings belonging to 1,44,437 members moved into EPFO's direct administration. Our article on the EPFO amnesty scheme covers the one-time window for trusts that lacked formal exemption.
The Board was also told how CITES 2.0, a UAN-based platform built by C-DAC, has changed service: claims settled automatically rose from 39% to 71%, rejections fell from 23% to 7.82%, and average settlement time dropped from 11.15 days to 2.57 days.
The 19 November 2026 Decisions, One by One
| Decision | Old position | New position |
|---|---|---|
| Systematic Withdrawal Plan (SWP) | Retiring member withdraws the whole corpus at once | Voluntary periodic payouts (monthly, quarterly or half-yearly); the rest stays invested |
| Minimum balance to be kept in the account | 25% of contributions | 10% |
| Waiting period for final withdrawal | 12 months | 2 months |
| EDLI exemptions | Legacy cases pending; expired exemptions unrenewed | Six-month window to renew; relief from contributions, interest and damages for the verified gap |
| Investment | No AIF route | Up to 3% of fresh accretion, in principle |
Why the SWP matters. A lump sum can be spent too fast. An SWP turns savings into a stream of income while the unpaid balance keeps earning interest. The member keeps ownership of the corpus, and a nominee can withdraw the balance or continue the instalments if the member dies. The plan is voluntary. PIB estimates that about 6.32 lakh members above 55 with balances over ₹5 lakh will be the first beneficiaries.
The minimum-balance change. Dropping the lock to 10% frees more savings for use. On contributions of ₹4,00,000, the locked amount falls from ₹1,00,000 to ₹40,000. A 2-month wait helps people who lose a job. The trade-off is plain: more flexibility today, less cushion in old age.
The same proposal introduces UAN-linked direct voluntary contributions and third-party micro-contributions (PIB gives customer tips as an example). Both work without an employer's payroll, aimed at gig and self-employed workers.
The EDLI relief is a transition fix for establishments that kept group insurance equal to or better than the statutory cover but never completed the exemption paperwork.
The Wider Ladder: Code on Social Security and the Jan Suraksha Schemes
EPFO covers the formal workforce. Article 41 (a Directive Principle) asks the State to secure public assistance in old age, sickness and unemployment. In the Seventh Schedule, social security and social insurance (Entry 23) and welfare of labour, including provident funds, invalidity and old age pensions and maternity benefits (Entry 24) are on the Concurrent List. Insurance (Entry 47), on the other hand, is in the Union List.
In November 2025 the Government brought 29 central labour laws into four Labour Codes: the Code on Wages, 2019, the Industrial Relations Code, 2020, the Code on Social Security, 2020 and the Occupational Safety, Health and Working Conditions (OSH) Code, 2020. The Code on Social Security merges nine social security laws, including the EPF Act, and for the first time brings gig and platform workers into the formal welfare net through a National Social Security Board. The OSH Code absorbs the Factories Act, 1948 and the Plantations Labour Act, 1951. Our article on the Social Security Board explains the gig-worker side.
| Scheme | Who it is for | What it gives |
|---|---|---|
| Atal Pension Yojana (APY) | Unorganised-sector workers aged 18–40 with a bank account | A guaranteed monthly pension of ₹1,000 to ₹5,000 from age 60, depending on contributions |
| PM Jeevan Jyoti Bima Yojana (PMJJBY) | Ages 18–50 | ₹2 lakh life cover on death, renewed each year for a premium under ₹450 |
| PM Suraksha Bima Yojana (PMSBY) | Ages 18–70 | ₹2 lakh on accidental death or total disability; ₹1 lakh for partial disability; premium ₹20 a year |
| PM Vaya Vandana Yojana (PMVVY) | Senior citizens 60 and above | An assured pension or return through LIC, backed by a government guarantee |
| National Pension System (NPS) | Any citizen; compulsory for central government employees who joined after 2004 | A market-linked pension account run by PFRDA |
APY, PMJJBY and PMSBY were launched together on 9 May 2015, and the Prime Minister has recently put APY's coverage at about 9 crore people. Our note on India's social security coverage shows how totals are counted. The link with livelihoods and the labour market is explained on our unemployment and labour page, and how the numbers are measured on the PLFS article.
Why Provident Funds and Pensions Matter to the Economy
A provident fund is a forced saving: a fixed share of every pay cheque is set aside, so households that would otherwise spend everything build a retirement fund by default. Because the money cannot be withdrawn for decades, it becomes long-term capital for government securities and other long-dated assets. It also rewards formalisation, since only workers on a registered payroll get cover, and it answers longevity risk, the chance of outliving your savings.
| Type | Meaning | Example |
|---|---|---|
| Defined contribution | The contribution is fixed. The final amount depends on returns, so the member bears the market risk | EPF, NPS |
| Defined benefit | The pension is fixed by a formula, so the scheme or the employer bears the risk | EPS (the ÷ 70 formula); the old government pension |
| Social pension | Paid from the budget with no personal contribution, targeted at the poor or elderly | National Social Assistance Programme pensions |
The Union Budget of 2025 raised the foreign investment cap in insurance from 74% to 100%. The savings system behind these accounts is on our banking page, and the group-based route to pension coverage is in our article on Pension Sakhis.
How UPSC Has Asked It: Past Papers Solved
These are real CDS questions on schemes, codes and the Seventh Schedule.
Which of the following is/are social security scheme(s)? 1. Atal Pension Yojana 2. Pradhan Mantri Jeevan Jyoti Bima Yojana 3. Pradhan Mantri Suraksha Bima Yojana
(a) 1 only (b) 2 and 3 only (c) 1, 2 and 3 (d) 1 and 3 only
Answer: (c). APY is a pension scheme, PMJJBY gives life cover and PMSBY accident cover, and all three were launched on 9 May 2015. Do not drop an insurance scheme just because it is not a pension.
Which one of the following Labour Codes notified by the Government of India incorporated various provisions of the Central Labour Acts such as the Factories Act, 1948 and Plantations Labour Act, 1951?
(a) The Occupational Safety, Health and Working Conditions Code, 2020 (b) The Industrial Relations Code, 2020 (c) The Code on Wages, 2019 (d) The Code on Social Security, 2020
Answer: (a). Factories and plantations concern conditions of work, so they sit in the OSH Code. The tempting option (d) merges the EPF Act and ESI Act, not the Factories Act.
Consider the following statements about a scheme launched by the Government of India: It was launched to provide social security during old age and to protect elderly persons aged 60 years and above against a future fall in their interest income due to uncertain market conditions. The scheme enables old age income security for senior citizens through provision of assured pension/return linked to the subscription amount based on government guarantee to Life Insurance Corporation of India (LICI). Identify the scheme.
(a) Pradhan Mantri Swasthya Suraksha Yojana (b) Pradhan Mantri Vaya Vandana Yojana (c) Liveability Index Programme (d) Rashtriya Vayoshri Yojana
Answer: (b). The clues "60 and above", "assured pension" and "LIC" point to PMVVY. Rashtriya Vayoshri Yojana gives assistive devices to elderly people below the poverty line, not a pension.
Which one of the following is not correct?
(a) Taxes on agricultural income is a subject under the State List (b) Price control is a subject under the Concurrent List (c) Insurance does not come under the Union List (d) Forests is a subject under the Concurrent List
Answer: (c). Insurance is Entry 47 of the Union List, so (c) is the incorrect statement. The other three are correct. Watch the word not.
Union Budget 2025 increased the Sectoral cap of FDI to 100 per cent from 74 per cent for:
(a) Telecom Sector (b) Power Sector (c) Defence Sector (d) Insurance Sector
Answer: (d). The insurance FDI limit moved from 74% to 100%.
Most questions test a one-line identification. Learn the Jan Suraksha schemes with ages and amounts, what each Labour Code merges, and where provident funds and insurance sit in the Seventh Schedule.
Practice MCQs (with answers)
- The Employees' Provident Funds and Miscellaneous Provisions Act was passed in
- 1948
- 1952
- 1972
- 1995
- The Employees' Deposit Linked Insurance (EDLI) scheme provides
- a lump-sum payment to the family if the member dies in service
- a monthly pension from 58
- health cover in hospitals
- an unemployment allowance
- A worker earns ₹12,000 a month. Of the employer's 12% contribution, 3.67% goes to the EPF account. How much is that each month?
- ₹1,000
- ₹1,440
- ₹440
- ₹2,400
- The Central Board of Trustees of the EPF is chaired by the
- Union Finance Minister
- Prime Minister
- Secretary, Labour and Employment
- Union Minister of Labour and Employment
- "Provident funds" and "social security and social insurance" are subjects in the
- Concurrent List
- Union List
- State List
- Residuary list
- Which scheme offers ₹2 lakh cover on accidental death for an annual premium of ₹20?
- PM Jeevan Jyoti Bima Yojana
- Atal Pension Yojana
- PM Vaya Vandana Yojana
- PM Suraksha Bima Yojana
- Under the Systematic Withdrawal Plan approved on 19 November 2026, a retiring EPF member can
- take only the entire amount at once
- give up ownership of the corpus
- receive periodic instalments while the rest of the corpus keeps earning returns
- withdraw only through the employer
- The Code on Social Security, 2020 merges how many central social security laws?
- 4
- 9
- 13
- 29
1-b, 2-a, 3-c, 4-d, 5-a, 6-d, 7-c, 8-b. Q3: 3.67% of 12,000 is 440; the ₹1,000 option is the 8.33% pension share, the usual trap. Q4: it is a minister, not a civil servant; the Central Provident Fund Commissioner is only the Member Secretary. Q6: PMJJBY is life cover for under ₹450, while PMSBY is the ₹20 accident cover. Q8: 29 is the number of laws combined into the four Codes, and 13 belongs to the OSH Code.
Quick Revision
- EPF Act, 1952 (20+ employees). Pots: EPF (savings), EPS 1995 (pension), EDLI (insurance). Employee 12% to EPF; employer 12% = 8.33% EPS + 3.67% EPF. EPS and EDLI are employer-paid. Pension = salary × service ÷ 70.
- Wage ceiling ₹15,000 → ₹25,000 (Cabinet, 16 Sep 2026; last revised Sep 2014; 51 lakh more covered).
- CBT: tripartite, chaired by the Union Labour Minister; CPFC is Member Secretary. UAN = one number for life.
- 19 Nov 2026: SWP; minimum balance 25% → 10%; wait 12 → 2 months; EDLI relief (6-month window); AIF up to 3% of fresh accretion; CITES 2.0 (auto-settled claims 39% → 71%).
- Nov 2025: 29 laws → 4 Labour Codes. Social Security Code merges 9 laws and covers gig workers; OSH Code absorbs the Factories Act and Plantations Labour Act.
- APY ₹1,000–5,000 pension (18–40); PMJJBY ₹2 lakh life cover; PMSBY ₹2 lakh for ₹20; PMVVY LIC pension for 60+. Seventh Schedule: provident funds and social security are Concurrent; insurance is Union.
Frequently asked questions
What are EPF, EPS and EDLI?
EPF is the provident fund, a savings corpus built from the employee's 12% and part of the employer's 12%. EPS is the pension scheme, funded by the employer's 8.33% share. EDLI is the insurance scheme that pays the family a lump sum if the member dies in service, paid for entirely by the employer.
How is the employer's 12% contribution divided?
It is split, not added on top. 8.33% of the pensionable wage goes to EPS and the remaining 3.67% goes to the member's EPF account. On a wage of ₹12,000 that is about ₹1,000 to pension and ₹440 to EPF.
What did the Central Board of Trustees decide on 19 November 2026?
At its 240th meeting the Board approved a voluntary Systematic Withdrawal Plan, cut the minimum balance from 25% to 10% and the waiting period for final withdrawal from 12 months to 2 months, approved EDLI exemption relief, and allowed up to 3% of fresh accretion into Alternative Investment Funds in principle.
What is the EPFO wage ceiling now?
The Union Cabinet approved a rise in the wage ceiling for mandatory EPFO coverage from ₹15,000 to ₹25,000 per month on 16 September 2026. The ceiling had been last revised in September 2014, and the change brings more than 51 lakh additional employees within the mandatory net.
How is the Code on Social Security different from the EPF Act?
The EPF Act, 1952 is a single law for provident fund, pension and insurance. The Code on Social Security, 2020 merges nine central social security laws, including the EPF Act, into one framework, and for the first time includes gig and platform workers. It is one of four Labour Codes that replaced 29 older laws in November 2025.
Related CDS / OTA Economics topics
Economy and polity together carry a quarter of the CDS GS paper
Cavalier's CDS/OTA batches connect schemes, laws and current affairs in one chain, with weekly PYQ tests.